A salvage title usually means a vehicle was declared a total loss and is not yet road-legal. A rebuilt title means the vehicle was repaired and passed a state inspection. Both brands stay with the vehicle and affect its value.
Title brands are how states record a vehicle's serious damage history. They protect future buyers by making that history visible, and they have a lasting effect on a vehicle's value, insurability, and financing. The names and rules vary by state, but most follow the same general pattern.
Salvage Title
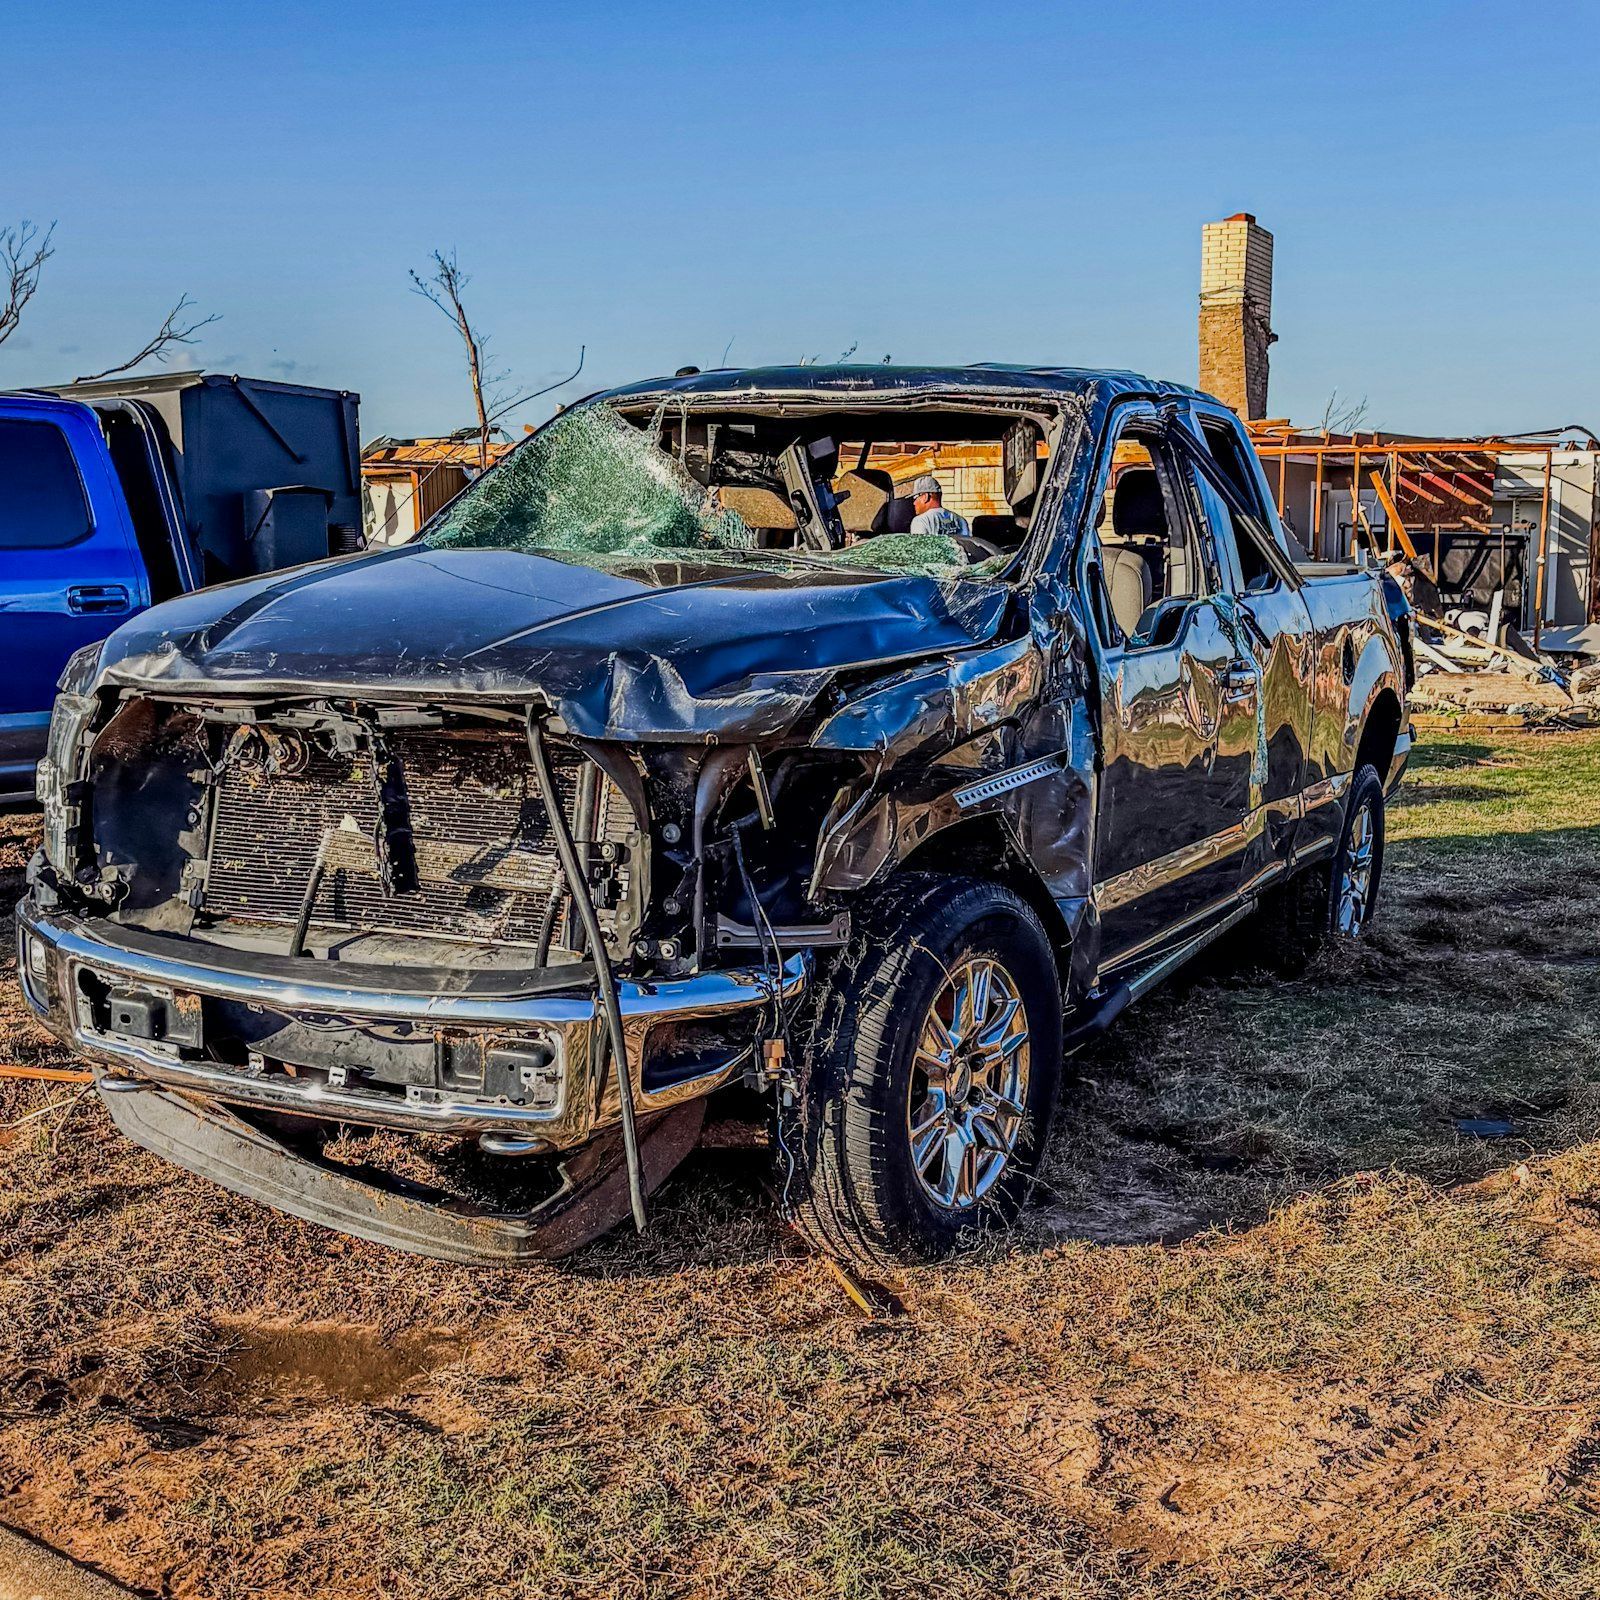
A vehicle usually receives a salvage title when an insurer declares it a total loss or when damage crosses a threshold set by state law. Our guide to when a car is considered totaled explains how that happens.
- A salvage vehicle generally cannot be registered or driven on public roads
- Salvage vehicles are typically sold at auction to rebuilders, dismantlers, or exporters
- Some states issue separate non-repairable or junk titles for vehicles that may never return to the road
Rebuilt Title
After a salvage vehicle is repaired, it can usually be inspected by the state. If it passes, it receives a rebuilt title, sometimes called reconstructed, restored, or prior salvage, depending on the state. A rebuilt vehicle can generally be registered and driven again.
State inspections commonly focus on whether stolen parts were used and whether required safety equipment is present. They are not necessarily a detailed inspection of repair quality, so a rebuilt title does not by itself confirm that structural repairs were done correctly.
How Title Brands Affect Value
| Title status | Typical market effect |
| Clean title | Full market value for the vehicle's age, mileage, and condition |
| Clean title with accident history | Often reduced value, depending on the severity of the damage |
| Rebuilt title | Significantly reduced value, with fewer interested buyers and dealers |
| Salvage title | Value based largely on parts or rebuild potential |
Many dealers will not retail rebuilt vehicles, and some lenders will not finance them, which narrows the pool of buyers and lowers prices.
Insurance on Rebuilt Vehicles
Insuring a rebuilt vehicle can be more difficult. Some insurers offer only liability coverage, and others require an inspection, photos, or repair documentation before offering collision and comprehensive coverage. If a rebuilt vehicle is later totaled, its actual cash value reflects the rebuilt title.
Thinking About Keeping Your Totaled Vehicle?
If you retain a totaled vehicle, it will usually carry a salvage title until it is repaired and inspected, and a rebuilt brand after that. Factor the reduced long-term value into your decision.
Buying a Vehicle With a Branded Title
- Get a vehicle history report and check the title history in every state the vehicle was registered
- Ask for repair invoices and photos of the damage and repairs
- Have a qualified collision repair shop inspect the structure and safety systems
- Confirm you can insure and finance the vehicle before you buy
- Price the vehicle based on comparable rebuilt vehicles, not clean-title vehicles
Frequently Asked Questions
Can a rebuilt title ever be changed back to a clean title?
Generally no. Title brands are permanent in most states and follow the vehicle even if it is registered in another state. Moving a vehicle to hide its brand, known as title washing, is illegal.
Is a salvage title the same as a total loss?
Not always. A salvage title often results from a total loss, but state rules differ on when a brand is required. Some totaled vehicles receive other brands, and some states brand vehicles based on damage thresholds.
Does a rebuilt title affect diminished value?
A rebuilt brand typically indicates the vehicle was previously declared a total loss, which significantly affects its market value. Diminished value claims, however, usually involve repaired vehicles that were never totaled.
Need Help Determining What Your Vehicle Is Worth?
Premier Vehicle Valuation Specialists provides independent, market-based vehicle valuations for diminished value and total loss claims, including appraisal clause representation and umpire services.
We review the available claim information first. If an appraisal is unlikely to add value, we will tell you.
This article provides general information about vehicle property damage claims and is not legal or tax advice. Insurance requirements, claim procedures, and available remedies vary by state, policy, and individual circumstances.