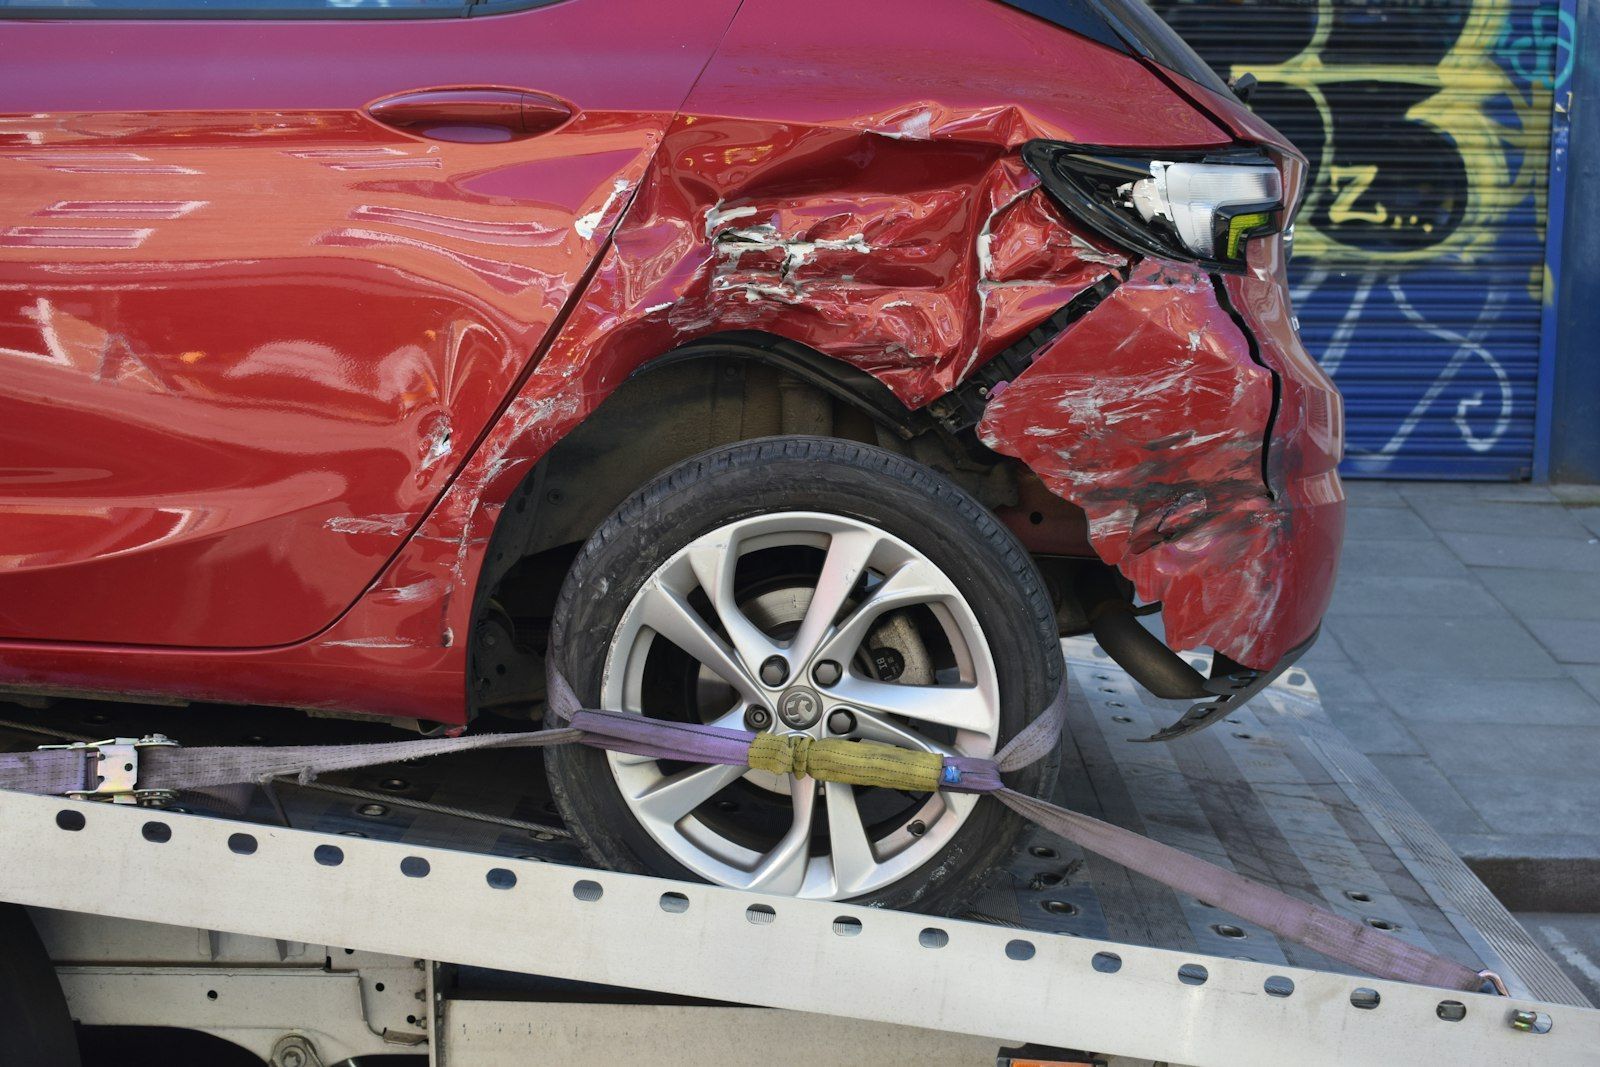
Electric vehicles are more likely to be totaled after moderate damage than many gas vehicles. The reasons usually come down to the battery pack, limited repair options, and the cost of parts and labor.
An EV owner may see damage that looks repairable, such as a scraped underbody, a damaged rear quarter panel, or a bent suspension component, and then be told the vehicle is a total loss. That outcome is common enough that it has drawn attention from insurers and repair professionals alike. Here is why it happens.
The Battery Pack Changes the Math
The high-voltage battery is usually the most expensive component in an electric vehicle, often a large share of the vehicle's value. It is typically mounted in the floor, where curb strikes, road debris, and undercarriage impacts can reach it.
- Even minor damage to the battery enclosure may require inspection or replacement
- Some manufacturers do not permit repairs to battery modules, so damage can mean replacing the entire pack
- Diagnosing internal battery damage can require specialized equipment and certified technicians
- Battery replacement alone can approach the actual cash value of an older or higher-mileage EV
When a battery replacement is part of the estimate, the repair cost can cross the total loss threshold quickly.
Other Factors That Raise EV Repair Costs
- Certified repair requirements. Some manufacturers require repairs at certified facilities, which can limit options and increase costs.
- Structural design. Some EVs use large single-piece castings or bonded structures that are difficult or impossible to section and repair.
- Parts availability. Longer waits for parts can increase rental and storage costs, which some insurers factor into the decision.
- Sensors and calibration. EVs often carry extensive driver-assistance hardware that must be replaced and calibrated.
- High-voltage safety procedures. Disabling and handling high-voltage systems adds labor time.
- Storage requirements. Some damaged EVs need to be stored apart from other vehicles because of fire risk, which can add cost.
How Value Plays a Role
A total loss decision compares repair cost with the vehicle's actual cash value. Used EV values have shifted significantly with price cuts on new models, changing incentives, and new model releases. When a vehicle's market value drops, the same repair is more likely to cross the threshold.
That is why an accurate valuation matters. If the actual cash value is understated, a vehicle can be totaled when it should not be, and the settlement will be too low. See our guide to how insurers determine actual cash value.
What to Check on an EV Total Loss Valuation
Confirm the battery size or range rating, drive configuration, trim, software-enabled features, and any premium driver-assistance packages. These details can significantly affect value and are easy to miss.
Comparable vehicles should match those details as closely as possible. A long-range version compared with standard-range listings, for example, can undervalue your vehicle.
If Your EV Is Repaired Instead
If your EV is repaired, especially after structural or battery-related work, its resale value may be affected. Buyers are often cautious about EVs with accident histories involving the battery or structure. That loss in value may support a diminished value claim.
Frequently Asked Questions
Can a damaged EV battery be repaired?
Sometimes. Some manufacturers and specialized shops repair or replace individual modules, but others require replacing the entire pack. The options depend on the manufacturer, the damage, and the repair facility.
Do EVs get totaled more often than gas cars?
EVs can be more likely to be totaled after moderate damage because battery, parts, and labor costs push repair estimates closer to the vehicle's value. Outcomes vary widely by model, age, and damage.
Does a totaled EV get a different settlement process?
No. The settlement is still based on actual cash value, plus any applicable taxes and fees, minus the deductible on a first-party claim. EV-specific features should be reflected in the valuation.
Think Your Total Loss Valuation Missed Something?
Premier Vehicle Valuation Specialists prepares independent, market-based total loss valuations and represents vehicle owners through the appraisal clause for a flat $449 fee.
Before you commit to anything, we review your claim information. If an appraisal is unlikely to make a meaningful difference, we will tell you.
This article provides general information about vehicle property damage claims and is not legal or tax advice. Insurance requirements, claim procedures, and available remedies vary by state, policy, and individual circumstances.