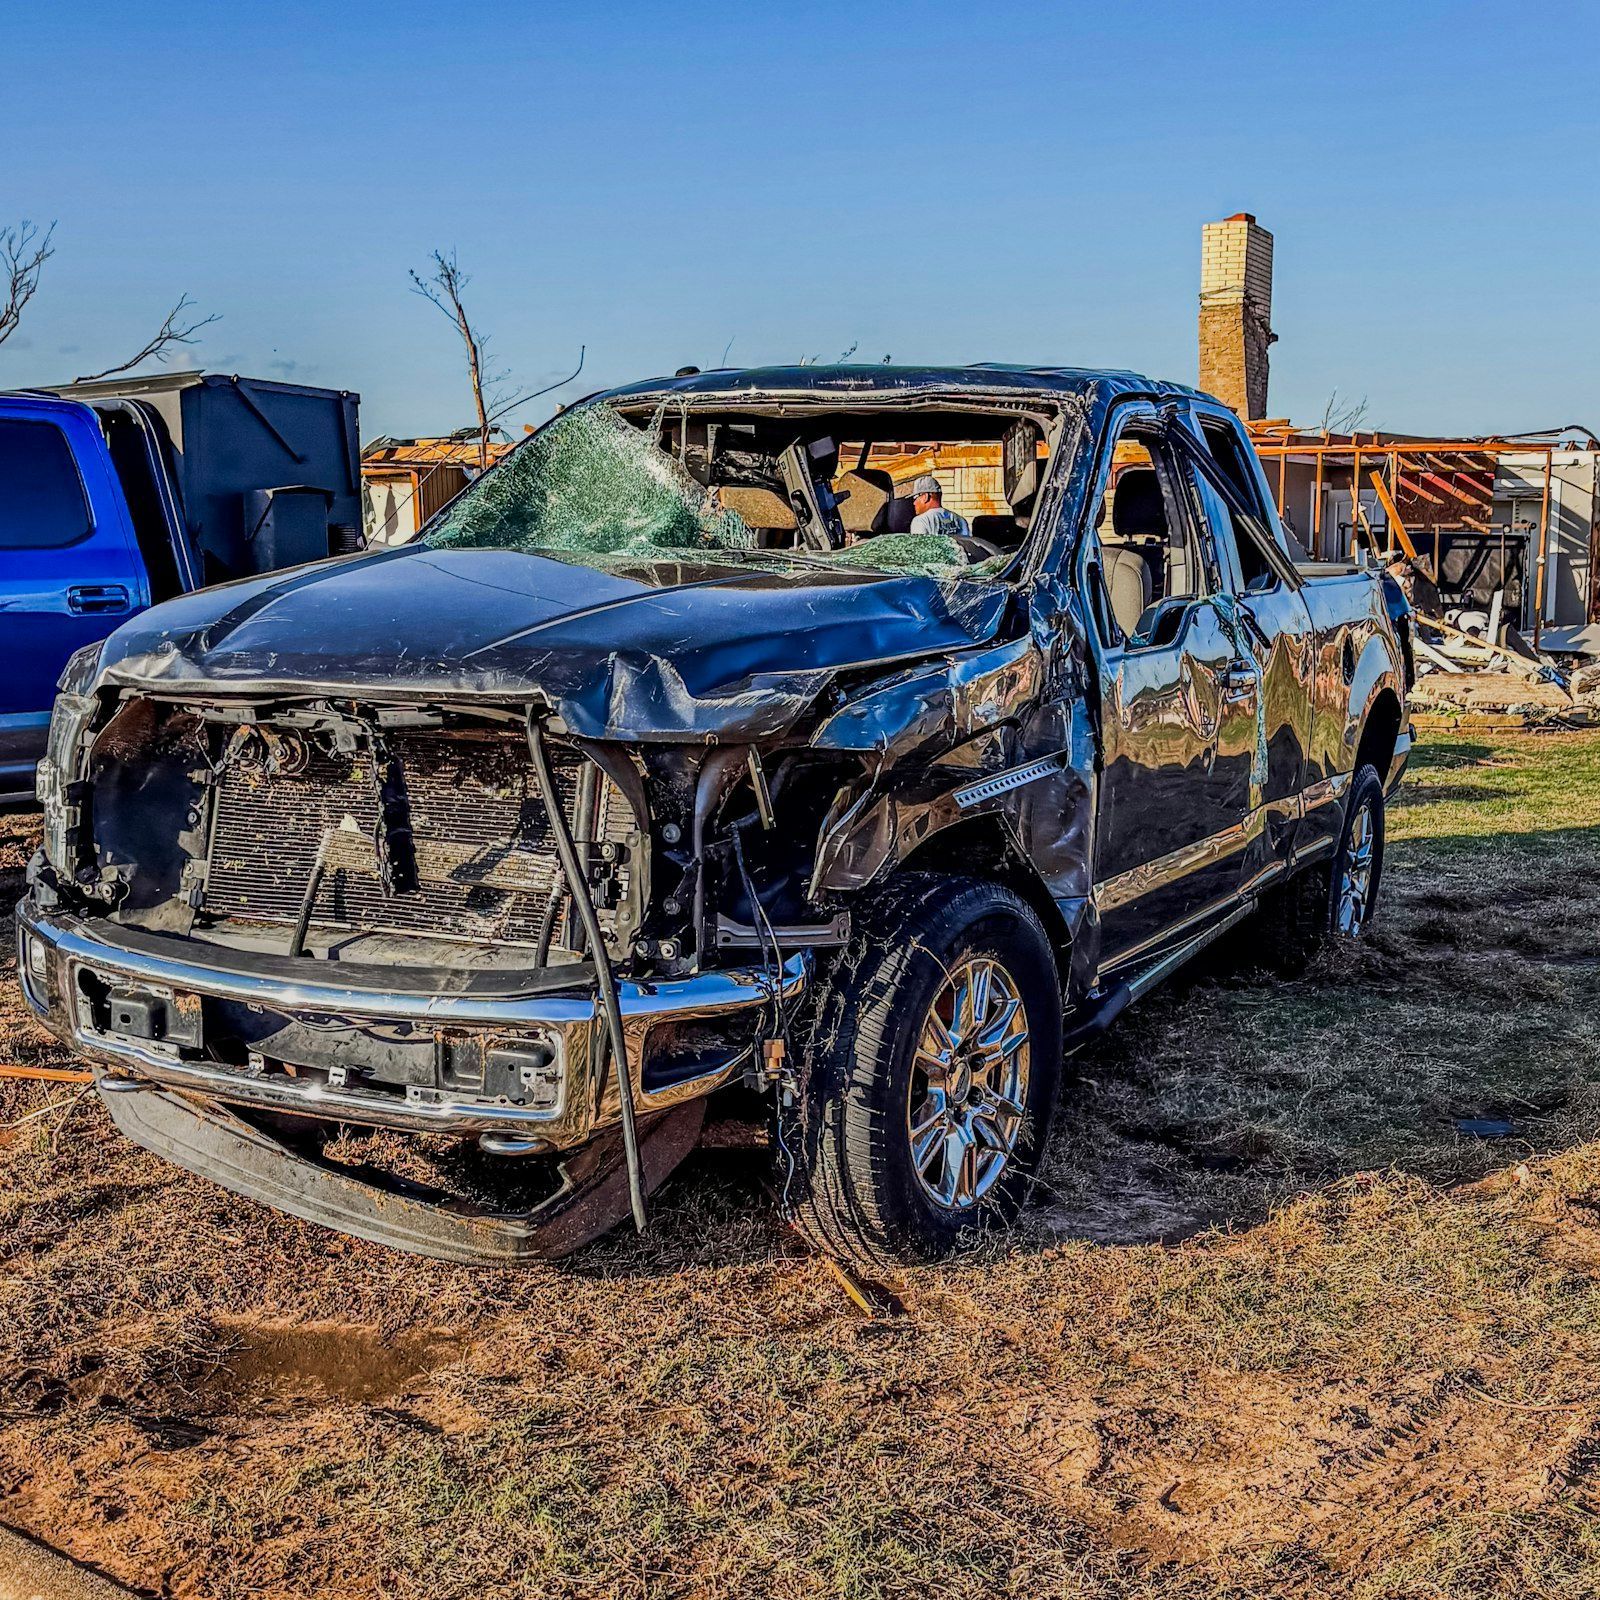
If your car is totaled while you are still making payments, the insurance settlement goes to your lender first. What happens next depends on whether the settlement is more or less than what you owe.
A total loss on a financed vehicle involves three parties: you, the insurance company, and the lender that holds the lien. Because the lender has an ownership interest in the vehicle, it is paid before you receive anything. Here is how the money moves and what to do if the numbers do not cover your loan.
Who Gets the Insurance Check?
The insurer issues payment to the lender up to the loan payoff amount. Any amount left over is paid to you. In some cases, the check is made out to both you and the lender.
Your loan payments do not stop just because the vehicle was totaled. Keep making payments until the lender confirms the loan has been paid off, or you risk late fees and credit damage while the claim is being processed.
When the Settlement Is More Than You Owe
This is the simpler scenario. The lender is paid in full, releases the lien, and you receive the remaining balance, which you can use toward a replacement vehicle.
| Example | Amount |
| Settlement (after deductible) | $21,000 |
| Loan payoff paid to lender | -$14,500 |
| Paid to you | $6,500 |
When You Owe More Than the Car Is Worth
This is often called being "upside down" or having negative equity. It is common in the first few years of a loan, especially with a small down payment, a long loan term, or a prior loan balance rolled into the new one.
| Example | Amount |
| Settlement (after deductible) | $21,000 |
| Loan payoff | $26,000 |
| Remaining balance you still owe | $5,000 |
The insurance settlement pays the vehicle's actual cash value, not your loan balance. Without additional coverage, you remain responsible for the difference, even though you no longer have the vehicle.
How Gap Insurance Helps
Guaranteed asset protection, or gap insurance, is designed to cover the difference between your vehicle's actual cash value and the amount you still owe. It is sold by auto insurers, lenders, and dealerships, and it is often built into leases.
What Gap Insurance Usually Covers
- The difference between the settlement and the remaining loan or lease balance
- In some policies, your insurance deductible, up to a set limit
What Gap Insurance Often Does Not Cover
- Negative equity rolled in from a previous vehicle, or only up to a limit
- Late fees and past-due payments
- Extended warranties, service contracts, and other add-ons financed into the loan
- Amounts above the policy's maximum, often stated as a percentage of the vehicle's value
Coverage terms vary significantly, so review your gap contract and contact the gap provider as soon as the vehicle is declared a total loss. Most gap providers will not pay until the primary insurance settlement is finalized.
Why an Accurate Valuation Matters Even More With Gap Coverage
Gap coverage is calculated from the primary insurer's settlement, and many gap contracts cap what they will pay. If the actual cash value is understated, the shortfall can grow beyond that cap, leaving you to cover the rest.
An accurate ACV helps everyone. Our guide to how insurers determine actual cash value explains what to check in your valuation.
What to Do If You Do Not Have Gap Insurance
1 Confirm the valuation is accurate
Review the valuation report line by line. A correct trim, options list, and mileage, along with truly comparable vehicles, can narrow the gap. If you disagree with the value, you may be able to dispute the total loss valuation.
2 Ask about refundable add-ons
Extended warranties, service contracts, and other products financed into the loan are often partially refundable when the vehicle is totaled. Those refunds are typically applied to the loan balance.
3 Check whether sales tax and fees are included
Depending on your state and policy, the settlement may need to include sales tax, title, and registration fees.
4 Talk to your lender
Ask about a payment plan for the remaining balance. Some lenders allow the remaining balance to be rolled into a new loan, but that carries the negative equity forward.
Frequently Asked Questions
Do I have to keep paying my car loan after a total loss?
Yes. Continue making payments until the lender confirms the loan has been paid off by the settlement. Missing payments while the claim is processed can result in late fees and credit reporting.
Is gap insurance worth it?
Gap insurance is most useful when you owe more than the vehicle is worth, which is common with small down payments, long loan terms, rolled-in negative equity, or vehicles that depreciate quickly. Once your loan balance falls below the vehicle's value, gap coverage is generally no longer needed.
Does gap insurance pay my deductible?
Some gap policies cover the deductible up to a set amount, and others do not. Check the terms of your specific gap contract.
Can I buy gap insurance after my car is totaled?
No. Gap insurance has to be in place before the loss occurs.
Think Your Total Loss Valuation Missed Something?
Premier Vehicle Valuation Specialists prepares independent, market-based total loss valuations and represents vehicle owners through the appraisal clause for a flat $449 fee.
Before you commit to anything, we review your claim information. If an appraisal is unlikely to make a meaningful difference, we will tell you.
This article provides general information about vehicle property damage claims and is not legal or tax advice. Insurance requirements, claim procedures, and available remedies vary by state, policy, and individual circumstances.